What Is a Safe Investment? Simple Guide


You want your money to be there when you need it. That wish sits behind every search for a safe investment. Safety sounds like a switch. In real life it is a sliding scale.
No option removes every risk. A product can protect your principal and still lose buying power. Another can grow for decades and still scare you in a bad year. Start with the job the money has to do.
What Is a Safe Investment?
A safe investment is money placed where you have a high chance of getting your principal back on time, with little price drama. The usual goal is protection first, growth second.
Cash in an FDIC-insured savings account is the plainest example. A short U.S. Treasury bill is another. A certificate of deposit at an insured bank can also fit if you can leave the money until maturity.
Safe does not mean “cannot lose anything in any sense.” Inflation can shrink what a dollar buys. A rate change can make an older bond less attractive if you sell early. A company promise is only as strong as the company.
Match safety to time. Money for rent next month does not belong in a stock fund. Money for retirement in 25 years can often take more market risk if you can stay invested.
How Safety Is Different From Return
Return is what you hope to earn. Safety is how bumpy the ride is, and whether you can get your cash when planned.
Higher expected growth usually comes with bigger swings. Stocks have historically outpaced cash over long stretches in the United States. They have also dropped 20% or more in hard years. That drop is not a glitch. It is the price of the growth.
A product that advertises a high yield is not automatically safe. High payouts can come from market risk, credit risk, lockups, or fees. Read the structure, not the headline rate.
Your emergency fund and your retirement account should not use the same definition of safe. One needs stability this year. The other needs growth that can beat inflation over decades.
Common Options People Call “Safe”
These tools are often used for principal protection. Details and limits still matter.
| Option | What it generally is | Main protection | Watch-outs |
|---|---|---|---|
| FDIC-insured savings or checking | Bank deposit | FDIC coverage within legal limits if the bank fails | Inflation, low yield |
| Credit union share accounts | Credit union deposit | NCUA coverage within limits at insured unions | Same inflation issue |
| Bank or credit union CDs | Time deposit | Deposit insurance within limits | Early-withdrawal penalty |
| U.S. Treasury bills, notes, bonds | Loans to the U.S. government | Backed by the Treasury | Price can move if you sell before maturity |
| Treasury I Bonds | Government savings bond | Principal protection with inflation-linked interest, subject to rules | Purchase limits, 12-month lock, early-redemption rules |
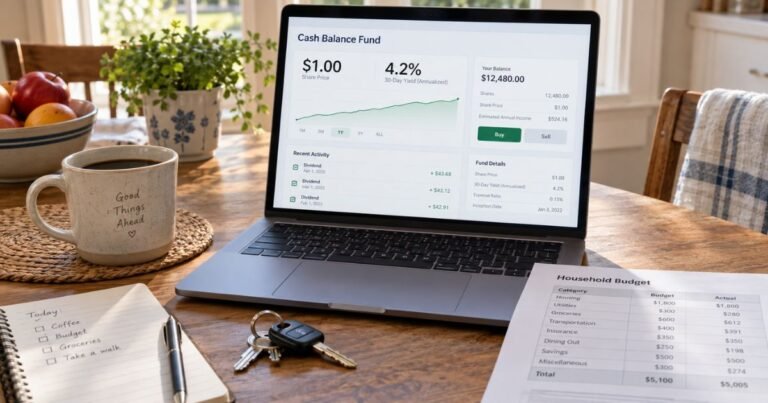
| Money market funds | Mutual fund or ETF that holds short-term debt | Not FDIC insurance | Value is managed to stay stable, but it is still an investment |
| Short high-quality bond funds | Basket of bonds | Diversification, not a guarantee | Share price can fall when rates rise |
FDIC insurance generally covers deposits up to $250,000 per depositor, per insured bank, per ownership category. That figure can change by law. Joint accounts and certain trust rules can affect how coverage adds up. Confirm current limits at fdic.gov.
NCUA insurance works in a similar way for most federally insured credit unions. Confirm at ncua.gov.
U.S. Treasuries are treated as among the lowest credit-risk investments because they are obligations of the federal government.
If you buy a bond and hold it to maturity, you generally receive the face value plus stated interest. If you sell early, the market price may be higher or lower.
Money market funds are not bank accounts. Government money market funds hold short Treasuries and similar paper. They aim for a stable share price. They can still face stress in rare market events.
Risks That Hide Inside “Safe”
Inflation risk.
Your balance can stay $10,000 while groceries cost more. Cash feels safe and slowly buys less.
Interest-rate risk.
When rates rise, existing bonds with lower coupons often fall in price. That matters if you need to sell a fund or a bond before it matures.
Liquidity risk.
A CD, annuity, or lockup period can protect a rate and still trap you. An early-exit fee is a real loss.
Credit risk.
A corporate bond or a private note depends on the borrower. A high rate can be a warning, not a gift.
Company and product risk.
An insurance guarantee depends on the insurer. An app can be regulated and still invest you in assets that drop.
Opportunity risk.
Parking 30 years of retirement savings in a 1% account can feel calm and still fall short of your goal.
Fraud risk. Unregistered notes, “guaranteed 20%” pitches, and look-alike websites are not safe investments. They are sales.
How to Judge Safety in Five Minutes
Ask what can go down. If the honest answer is “the share price,” it is not cash-like.
Ask who stands behind the promise. A bank deposit, a Treasury, and an insurance contract use different backstops.
Ask when you need the money. Under three years usually favors cash, short CDs, or short Treasuries for many people. Over ten years, a diversified stock mix has historically been the growth engine, with no year-by-year promise.
Ask what you pay. Fees on a “safe” wrapper can erase a thin yield.
Ask whether you understand the exit. If you cannot explain the penalty in one sentence, wait.
Building a Mix Instead of One Magic Product
Most households need more than one bucket.
Bucket one is cash you can reach. This is the emergency fund. Many people aim for a few months of necessary expenses. Use an insured savings account or a similar deposit.
Bucket two is money for a known bill in the next few years. A CD ladder or short Treasuries can fit. You trade a little yield for a date you can plan around.
Bucket three is long-term growth. Broad, low-cost stock and bond funds live here. This bucket is not “safe” month to month. It is how many people try to stay ahead of inflation for retirement.
The mix is the safety tool. A 25-year-old and a person who retires next spring should not copy each other.
Revisit the mix when your life changes. A new baby, a home purchase, or a job loss can move money from growth back to cash.
What Usually Does Not Qualify as Safe
Individual stocks can be fine as a small satellite. They are not a safe core.
Cryptocurrency can move sharply in both directions. Treat it as speculative if you use it at all.
High-yield private deals pitched at dinners often lack the disclosures of a public fund. Guaranteed language plus urgency is a red flag.
Variable annuities and complex indexed products can include guarantees on paper. Fees, surrender charges, and market pieces can still make them a poor fit for money you call safe.
Past performance is not a lock. A fund that rose for five years can fall in year six.
Simple Habits That Protect You
Keep insured deposits within coverage limits, or spread them across ownership categories and institutions if balances are large.
Use official sites. Banks, Treasuries, and brokerages have real domains. Search ads can lead to copies.
Turn on two-factor login. Account takeover is a more common household risk than a Treasury default.
Write the purpose on the account. “Car replacement 2028” stops you from raiding it for a sale.
Increase risk only with money you can leave invested through a slump. If a 20% drop would force a sale, the allocation is too aggressive.
FAQs About What is a Safe Investment
Q. What is a safe investment for money I need soon?
A. For money you need within months, an FDIC-insured savings account or a similar insured deposit is the usual starting point. Short Treasuries or short CDs can also fit if you can meet the timeline. Stocks are generally a poor match for next month’s bills.
Q. Are money market funds as safe as savings accounts?
A. Not in the same legal way. A savings account at an insured bank can have FDIC coverage. A money market fund is an investment that aims for stability. Government funds are often used as a cash-like tool, but they are not deposit insurance.
Q. Is there any investment with zero risk?
A. No option removes every risk. Cash can lose buying power. Bonds can lose market value if sold early. Stocks can fall. Safety means the risks that remain are ones you understand and can live with.
Q. Should all of my money be in safe investments?
A. Usually no, if you have long-term goals. Too much cash can make it harder to keep up with prices over decades. Many people keep a safe bucket for near-term needs and a growth bucket for later goals.
Conclusion
A safe investment is one that is likely to return your principal when you need it, with limited surprises. Insured deposits and short U.S. government paper sit at the conservative end.
Name the deadline first. Then pick the tool. Safety is a plan with buckets, not a single product that does every job.
Disclaimer
This article is for general education only. It is not financial, tax, or investment advice. All investing and cash holdings involve some form of risk, including inflation and possible loss of principal in market products. Insurance limits, Treasury rules, and account features vary and can change. Verify current FDIC, NCUA, and Treasury details on official sites, and consider a licensed advisor for questions about your own money.