What Do Apartments Look For On Bank Statements? Explained

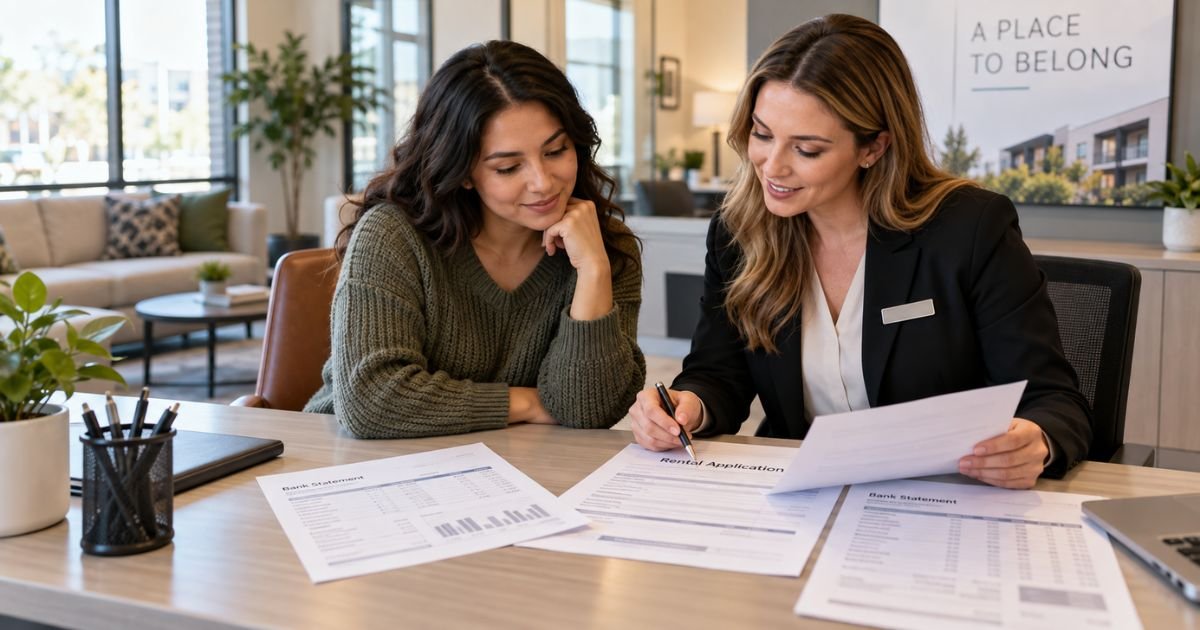
If an apartment asks for bank statements, you may wonder how closely someone will read them. In most cases, the goal is simple. The property wants proof that the income you listed is real and that rent looks affordable.
Not every building asks for statements. Many start with pay stubs, a credit check, and rental history. Bank records usually come up when your income is harder to verify or when the property wants extra proof of funds.
What Apartments Look For on Bank Statements
Apartments typically use bank statements to confirm cash flow, not to judge every purchase you make. A leasing office wants to see that money arrives on a regular schedule and that your account can support rent plus everyday bills.
Most properties compare your statements with the rest of your application. Deposits should line up with pay stubs, an offer letter, benefit records, or tax forms. If the numbers do not match, you may get follow-up questions.
A common industry guideline is that gross monthly income should be about three times the rent. That is a screening rule of thumb, not a nationwide law. Some properties use a different multiple, especially in high-cost cities.
Statements also help a landlord see whether you have enough cash for move-in costs. First month’s rent, a security deposit, and any admin fees are often due at once.
Why an Apartment Asks for Bank Statements
A pay stub shows what an employer says you earned. A bank statement shows what actually landed in your account after taxes and deductions.
That extra check is more common if you are self-employed, paid by 1099, starting a new job, or using savings as part of your qualification. It can also come up if your credit file is thin or your income varies from month to month.
Property managers also use statements to reduce document fraud. Altered pay stubs are a known problem in rental screening. Official bank PDFs are harder to fake and easier to match against other records.
Some offices now offer bank-linked verification instead of uploaded PDFs. That option pulls deposit data directly from your bank. Ask what the tool shares before you connect an account.
How Many Months They Usually Want
Many apartments ask for the most recent two or three months. That window is usually enough to see a pattern.
Self-employed renters and gig workers may be asked for a longer period, often three to six months. A longer sample can smooth out a slow month or a large project payment.
If you just started a job, one recent statement plus an offer letter may be accepted. The property may still want proof of your previous income until the new pay cycle shows up.
Ask the leasing office for the exact range before you upload anything. Sending extra months can add details you did not need to share.
The Income Deposits They Review First
The first pass is usually the deposit column. Reviewers look for repeating payroll deposits, benefit payments, or client payments that match what you claimed.
They may look for:
- Regular deposits from an employer, payroll provider, or benefits agency
- Amounts that make sense next to your pay stubs or award letter
- A schedule that looks weekly, biweekly, or monthly
- Combined income from more than one account, if you disclosed those accounts
A one-time deposit is usually not treated as ongoing income. A tax refund, gift, bonus, or transfer from savings can raise your balance, but it may not count toward the three-times-rent guideline.
If you are paid through a gig platform, the deposit name may not match your job title. A short note that explains “Stripe,” “PayPal,” or a platform name can prevent confusion.
Balances, Reserves, and Move-In Money
After deposits, many reviewers look at your ending balance. They want to see that you can cover move-in costs without emptying the account.
There is no single required savings number. Some private landlords like to see a cushion equal to a month or two of rent. Large management companies may care more about income than a high balance.
What often matters is the pattern. An account that stays near zero until payday, then drops again, can look tight. A declining balance across several months can also raise questions.
If your money sits in a savings account, ask whether that statement counts. Many properties will accept it if the account is in your name and the funds are available.
Red Flags That Can Trigger Extra Questions
One imperfect month does not always sink an application. A repeating pattern is what usually stands out.
Properties may look more closely at:
- Repeated overdrafts or NSF fees
- Returned payments or unpaid item charges
- Regular payday-loan or cash-advance activity
- Large unexplained deposits right before you apply
- Balances that fall far below the rent amount each month
- Documents that look cropped, edited, or incomplete
Some reviewers also notice late-fee charges from utilities or other bills. That can look like a timing problem, even if your income is high enough on paper.
Spending categories are not a formal scoring system at every building. Still, a statement full of cash-flow stress can make a borderline file harder to approve.
Do not edit deposits, dates, or balances. Many screening teams now use software that flags altered PDFs. If something needs context, add a short written explanation instead.
How Your Statements Should Match Other Paperwork
Bank statements are rarely reviewed alone. The leasing office is looking for one consistent story.
Your name should match your ID and application. The employer or income source should match your pay stubs or tax forms. Net deposits should be in the same range as take-home pay after taxes.
If you split income across two banks, say so up front. A reviewer who sees only one account may think you earn less than you do.
If a roommate, partner, or parent helps with rent, ask whether that person must apply or sign as a guarantor. A large transfer from someone else may not count as your income unless the property accepts it.
What You Can Hide and What You Should Leave Visible
You can often protect some private details. Ask the property first, because rules vary.
Many offices accept statements with the full account number and routing number covered, as long as the last few digits and the bank name remain visible. You can usually hide a Social Security number if it appears on the page.
Leave these items readable:
- Your name
- Bank name and statement dates
- Opening and ending balances
- Income deposits
- Any pages the office requested
Do not hide the transactions that prove your income. A heavily blacked-out statement can look incomplete and slow the review.
Download an official PDF from your bank when you can. Photos and screenshots are easier to reject.
Safer Ways to Share Statements
Confirm that the listing is real before you send financial documents. A legitimate apartment should let you tour the unit or verify the management company.
Use the property’s official application portal when one exists. Avoid emailing statements to a personal address that does not match the building or listed owner.
A bank statement is not the same as your account number and login. Some applications ask for account numbers later to set up autopay. You can usually wait until you are approved and the lease is ready.
If you are not comfortable uploading statements, ask what else they accept. Recent pay stubs, a W-2, tax returns, a benefit award letter, or an employer letter may be enough.
A guarantor or extra deposit is sometimes an option when income is close to the cutoff. Those options depend on the property’s written screening policy.
How to Make Your Statements Easier to Approve
Give the office a clean package. Label each file with your name and the month.
If your income varies, add a one-page summary of average monthly deposits. Point to the lines that are wages, benefits, or client payments.
If a large deposit needs context, explain it in one or two sentences. “Transfer from savings for moving costs” is clearer than leaving a reviewer to guess.
If last month included an unusual expense or an overdraft, waiting for the next statement can help when you have time. Recent months usually carry the most weight.
Apply the same documents to every adult who will sign the lease. Mixed or missing files are a common reason applications stall.
FAQs About What Apartments Look For on Bank Statements
Q. Do all apartments require bank statements?
A. No. Many properties accept pay stubs, tax forms, or an employer letter instead. Statements are more common when income varies, you are self-employed, or the office wants extra proof of funds.
Q. How many months of bank statements do apartments usually want?
A. Two to three recent months is a typical request. Self-employed or gig workers may be asked for a longer period. Always confirm the property’s written requirement before you upload files.
Q. Can I black out personal purchases on my bank statements?
A. Sometimes, if the office agrees. You can often hide full account numbers and unrelated personal details. Leave your name, dates, balances, and income deposits visible so the reviewer can verify affordability.
Q. What if my bank statements show overdrafts or a low balance?
A. One issue may not end the application, but repeated overdrafts or a balance that cannot cover rent can lead to extra questions or a denial. Ask whether a guarantor, extra deposit, or other income documents can help.
Conclusion
What apartments look for on bank statements is usually proof of steady income, enough cash for move-in costs, and a file that matches your application. They are less interested in every store charge and more interested in whether rent looks sustainable.
Send official recent statements, keep the income lines easy to see, and ask what you may redact. When the deposits, balances, and other documents tell the same story, the review tends to go faster.
Disclaimer
This article is for general information only. It is not legal, housing, or financial advice. Screening rules, income multiples, document lists, and privacy practices vary by property, city, and state. Confirm requirements with the landlord or management company, and verify any listing before you share bank records.