Uplifted Life Charge On Credit Card Statement [Uncovered]

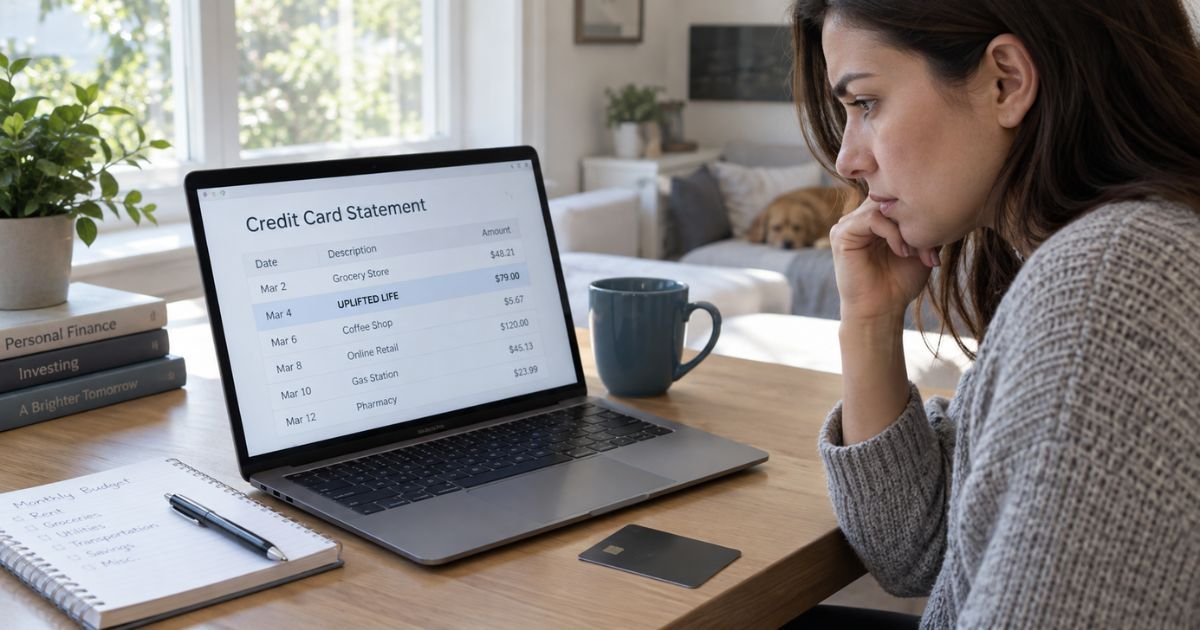
An Uplifted Life charge on credit card may be connected to a purchase or recurring membership from Uplifted Life, an online retailer operating at UpliftedLife.us.
If the charge seems unfamiliar, check whether you previously bought a product from the site or enrolled in its VIP membership.
If you still don’t recognize it, contact your card issuer promptly rather than assuming the transaction is legitimate.
What Is the Uplifted Life Charge on Your Credit Card?
Uplifted Life operates an online store selling a range of consumer products. Its current website lists items such as clothing, household products, accessories, planners, and other merchandise.
The company also advertises a VIP membership program. Its membership page states that the membership becomes a recurring charge after an introductory period.
This means an Uplifted Life transaction could represent either:
- A direct product purchase
- A VIP membership payment
- A recurring membership charge following an earlier purchase or enrollment
- Another transaction processed under the Uplifted Life merchant name
The exact descriptor shown by your bank can vary because card issuers and payment processors may shorten or format merchant names differently.
Seeing the name doesn’t by itself prove that a transaction is fraudulent. You should compare the date and amount with your receipts, emails, and past purchases before deciding what happened.
Why You May See a $29.99 Uplifted Life Charge
One amount worth checking is $29.99.
Uplifted Life currently lists its VIP Membership Club at $29.99 per month. Its membership page states that customers are charged $29.99 per month after a 12-day introductory period unless they cancel.
So, if your statement shows an Uplifted Life charge for $29.99, a recurring VIP membership is one possible explanation.
However, don’t assume every $29.99 transaction has the same cause. Your account history, transaction date, and purchase records are more reliable ways to confirm the source.
How an Uplifted Life Membership Can Become Recurring
According to Uplifted Life’s current membership page, its VIP program includes special product pricing, shipping benefits on qualifying future orders, and access to membership offers.
The company says regular monthly billing begins after a 12-day introductory period and continues until cancellation.
This can make a later transaction harder to recognize if you remember purchasing a product but don’t remember the membership portion of the checkout or offer.
Complaints published by the Better Business Bureau also show that some consumers have reported recurring Uplifted Life charges after earlier purchases. These complaints reflect individual consumer allegations and shouldn’t be treated as independently verified proof about every transaction.
How to Verify an Uplifted Life Transaction
Before disputing the charge, spend a few minutes checking whether you can match it to something you authorized.
Start with the transaction details in your banking app. Look at the full merchant descriptor, amount, date, and whether the transaction is marked as pending or posted.
Next, search your email for terms such as:
- Uplifted Life
- UpliftedLife
- VIP membership
- Order confirmation
- Subscription
- Membership confirmation
Also check your browser history, text messages, PayPal records, or digital wallets if you commonly use them for online shopping.
Ask other authorized cardholders whether they made the purchase. A spouse, partner, or family member may recognize a transaction that you don’t.
If you find an earlier Uplifted Life purchase followed by regular monthly transactions, that pattern may indicate membership billing.
Is the Uplifted Life Charge a Scam?
An Uplifted Life charge isn’t automatically a scam.
There is an active Uplifted Life retail website with products, a membership page, and a membership cancellation page. The site explicitly lists its VIP membership as a monthly recurring product.
At the same time, BBB records include consumer complaints concerning unexpected or disputed recurring charges. Those complaints represent the consumers’ accounts of their experiences, not a finding that every Uplifted Life transaction is unauthorized.
The important question is whether you authorized your particular charge.
If you recognize the merchant and knowingly accepted a recurring membership, the charge may be valid. If you never made the purchase, never approved a membership, or believe the amount differs from what you agreed to, contact your card issuer.
How to Cancel an Uplifted Life Membership
Uplifted Life currently provides a dedicated membership cancellation page.
The page instructs VIP members to submit its cancellation form and write “Cancel My Membership” in the message field. The company states that a team member will cancel the membership before the next billing.
Its broader membership page also lists cancellation options and says cancellations should be made at least three business days before the next billing date.
When cancelling, keep evidence of your request.
You may want to save:
- A screenshot of the cancellation confirmation
- The date and time you submitted the request
- Relevant emails
- Order numbers
- Copies of previous statements showing recurring charges
Don’t assume cancelling a membership automatically refunds earlier payments. Cancellation and refunds are separate issues, and the outcome may depend on the merchant’s terms and your circumstances.
What to Do If You Don’t Recognize the Charge
If you’ve checked your records and still can’t identify the transaction, contact the card issuer using the number printed on the back of your card.
Tell the representative that you don’t recognize an Uplifted Life charge and ask for the full merchant information associated with the transaction.
Your issuer may be able to provide details that aren’t visible on your regular statement.
If you believe someone used your card without permission, ask the issuer about:
- Disputing the unauthorized transaction
- Blocking additional transactions when appropriate
- Replacing the card if its details may be compromised
- Reviewing your account for other unfamiliar charges
The Consumer Financial Protection Bureau recommends notifying your credit card company promptly when disputing a transaction.
Don’t rely only on contacting the merchant if you genuinely believe your card details were used without authorization.
How to Dispute an Uplifted Life Credit Card Charge
If the merchant doesn’t resolve the issue or you believe the transaction is unauthorized, you may be able to dispute it with your card issuer.
The CFPB says you should call your credit card company promptly. To preserve your federal billing-error rights, it also advises sending a written billing-error notice within 60 calendar days after the statement containing the charge was sent to you.
The FTC gives similar guidance under the Fair Credit Billing Act. It recommends sending written disputes to the issuer’s billing-inquiry address rather than the address used for payments.
Your notice generally should identify:
- Your name and account information
- The disputed transaction
- The amount
- Why you believe the charge is incorrect
- Any supporting documents you have
Keep copies of everything you submit.
The CFPB notes that if you’ve already paid the charge, you can still dispute it, although you may not receive the money back until the issuer completes its investigation.
Credit Card vs. Debit Card Disputes
The process can differ depending on whether Uplifted Life charged a credit card or debit card.
The Fair Credit Billing Act provides specific billing-error protections for credit card accounts. The FTC states that unauthorized credit card charges can qualify as billing errors.
Debit-card transactions generally fall under different federal rules governing electronic fund transfers.
If an unauthorized transaction came directly from your bank account through a debit card, report it immediately. CFPB guidance notes that the timing of your report can affect your protections in certain debit-card situations.
Regardless of the card type, reporting unfamiliar transactions quickly is usually the safest approach.
Could Replacing Your Card Stop Future Charges?
Replacing a compromised card may help prevent further unauthorized use, but don’t use card replacement as a substitute for cancelling a legitimate subscription.
If you enrolled in a recurring service, contact the merchant to cancel it according to its stated procedure.
If you never authorized the transaction, tell your issuer that you believe it is unauthorized and follow the issuer’s security instructions. The bank can determine whether replacing your card or taking additional account-security measures is appropriate.
Continue checking later statements after cancellation or a dispute. This helps you spot any further billing quickly.
FAQs About Uplifted Life Charge On Credit Card
Q. What is Uplifted Life on my credit card statement?
A. It may represent a purchase from UpliftedLife.us or billing for its VIP membership program. Check the amount, date, receipts, and previous purchases to confirm the source.
Q. Why did Uplifted Life charge me $29.99?
A. Uplifted Life currently lists a VIP Membership Club at $29.99 per month after an introductory period. A $29.99 transaction may therefore be a membership payment, although you should verify your individual transaction.
Q. How do I stop Uplifted Life from charging my card?
A. If the charge comes from a membership you authorized, use Uplifted Life’s cancellation process and keep proof of cancellation. If you didn’t authorize the transaction, contact your card issuer promptly.
Q. Can I dispute an Uplifted Life charge?
A. Potentially. If you believe the charge is unauthorized or otherwise qualifies as a billing error, contact your card issuer. Federal credit card billing-error protections include important deadlines, including a 60-day written-notice period in many cases.
Conclusion
An Uplifted Life charge on credit card may be connected to an online purchase or the company’s recurring VIP membership. A $29.99 charge is particularly worth checking against the current monthly membership price.
Review your receipts and emails first. If you can’t verify the transaction, contact your card issuer promptly, especially if you believe the charge wasn’t authorized.
Disclaimer
This content is for informational purposes only and isn’t financial or legal advice. Merchant policies, card protections, charges, and issuer procedures may vary, so verify account-specific questions with Uplifted Life, your financial institution, or your card issuer.